Reclaim your dividend withholding tax on international investments
If you received dividend income from overseas, it’s likely you are not receiving the full benefit of your investment. Sprintax Dividends will help you reclaim your withholding tax refund
How do investors reclaim Dividend Withholding Tax?
A DWT reclaim (or refund) is the process of recovering overpaid withholding tax after a dividend has already been paid.
Unlike relief at source, where the reduced treaty rate is applied upfront, the source country deducts tax at the full statutory rate at the time of payment and the investor subsequently submits a claim to recover the excess above the treaty rate they’re entitled to.
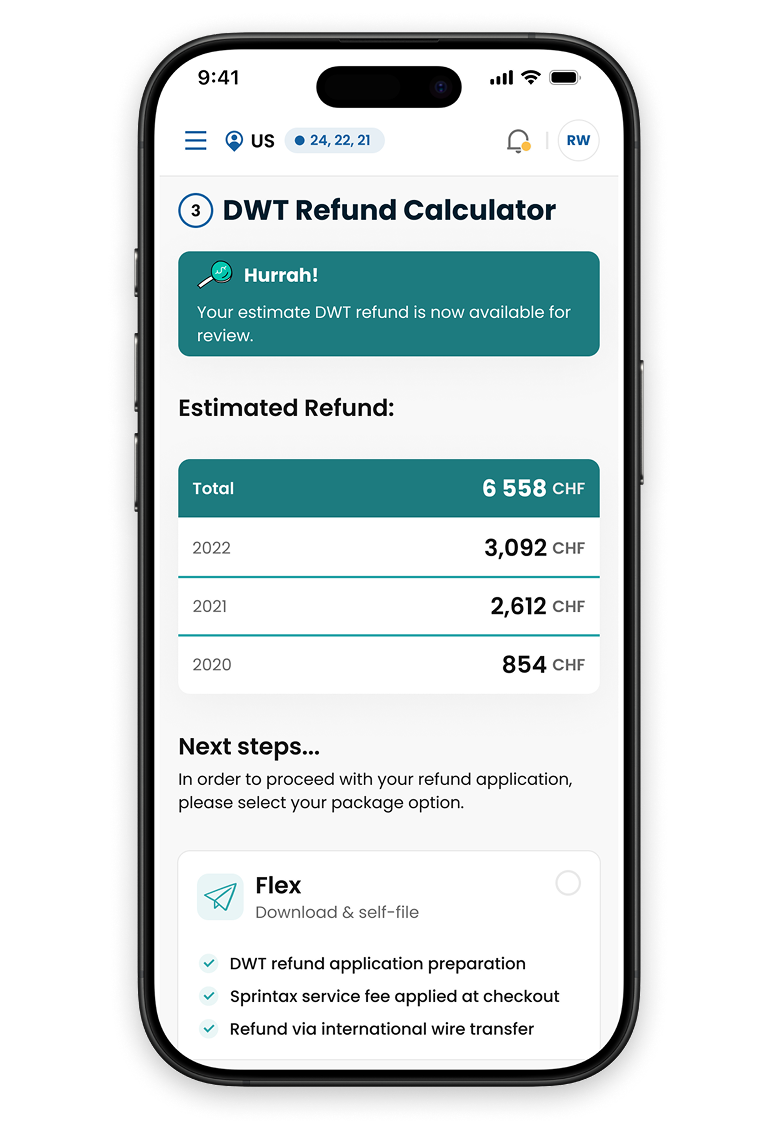
Sprintax Dividends will guide you through the reclaim process from start-to-finish, helping you gather the right documentation and submit your claim correctly the first time.
Which countries offer recovery of dividend withholding tax?
Withholding tax reclaim is the default recovery route in most markets, and it’s typically available anywhere a tax treaty exists between the investor’s country of residence and the country paying the dividend.
Requirements, deadlines and processing times vary significantly by country. Some tax authorities process claims within months, others take considerably longer — so it’s worth checking the specific rules that apply to your holdings.
* Specific treaty rate dependent on investor's country of residence
DWT reclaim in practice — a real-world scenario
Sprintax Dividends recently helped a Swiss company reclaim more than $1m in overpaid Dividend Withholding Tax for their employees.
The company offered employees worldwide shares through a global stock plan. However, Switzerland applies a 35% withholding tax on dividends. Many employees were entitled to reclaim part of this tax, but no process was in place to recover it — leaving thousands of dollars unclaimed by employees.
Sprintax Dividends supported the organization in implementing a comprehensive reclaim process, identifying eligible employees, preparing the required documentation, and filing the forms with Swiss tax authorities. Within 12 months, employees across 15 countries had reclaimed more than $1,000,000 in withheld dividend tax, averaging $2,454 back per employee.
-
The dividend is paid and tax is withheld
The paying company or its agent deducts withholding tax at the full statutory domestic rate, not the treaty rate.
-
The investors prepares and submits their claim to the tax office
In order to prepare a refund application, the investor will typically need a Certificate of Residence, proof of beneficial ownership, and evidence of the dividend received (such as a broker statement or tax voucher).
-
Claim reviewed by the tax office
The local tax authority reviews your document and verifies your refund entitlement.
-
The refund is issued
Refund timelines can vary widely by country, from a few months to multiple years in some cases.
Your questions, answered
Form 25 is the application non-Swiss residents use for a Swiss dividend withholding tax (Verrechnungssteuer) reclaim (for tax deducted from dividends and other investment income).
If you live outside Switzerland, hold Swiss securities and have had the full 35% tax rate withheld, you can apply for a tax refund by filing Form 25 (together with a Certificate of Residence and supporting broker documentation) to the Swiss Federal Tax Administration.
Germany withholds Kapitalertragsteuer at 26.375% (25% tax plus a 5.5% solidarity surcharge) on dividends paid to nonresidents. To apply for a german dividend withholding tax reclaim you must file a refund application with Germany’s Federal Central Tax Office (Bundeszentralamt für Steuern).
Kildeskatt is Norway’s withholding tax on dividends paid to shareholders who aren’t tax resident in Norway.
The standard tax rate is 25%. As an international investors, if you haven’t already benefited from a reduced treaty rate at the time of payment, you can apply to Norway’s tax authority (Skatteetaten) for a refund of the difference.
You have five years from the year in which your dividend was received to submit the claim.
For most UK dividends, there’s typically nothing to reclaim. The UK generally doesn’t withhold tax on ordinary dividends paid by UK companies to nonresidents.